portfolio · mmxxvi
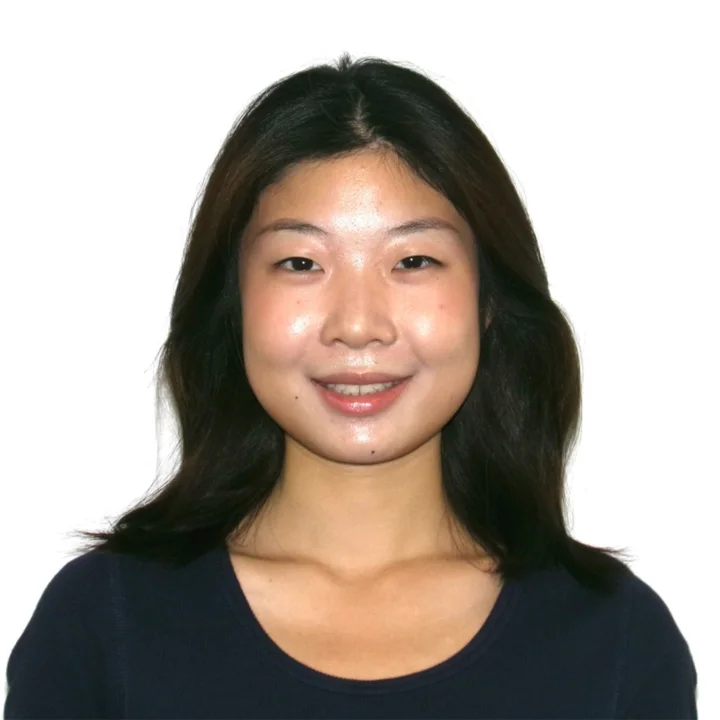
VanessaFeng
A data scientist and economist working where statistics meets markets: credit, portfolio, and quantitative risk.
UC San Diego ’27 · incoming Analyst, J.P. Morgan
01about
I turn messy financial data into something calm and legible.
San Diego, CA
I study data science and economics at UC San Diego, and most of my work lives where statistics meets markets: probability-of-default models, portfolio rebalancing, and the quiet plumbing that helps risk teams sleep at night.
I’ve worked across asset management, wealth management, credit risk, and venture, and I’m heading back to J.P. Morgan full-time after graduation. I care about models that are accurate and explainable, dashboards people actually open, and a threshold that catches the right loans.
- trilingual · en · 中文 · fr
- SIE & Bloomberg certified
- Monte Carlo enthusiast
- favorite animal: the orca
- painter since childhood
02experience
Where I’ve been diving in.
- Jun 2026 → Aug 2026J.P. MorganAsset Management Summer AnalystNew York, NY · asset management
- Aug 2025 → Sep 2025Morgan StanleyWealth Management Intern, Portfolio Risk ManagementNew York, NY · portfolio risk
- May 2025 → Aug 2025Lima One CapitalCredit Risk InternGreenville, SC · private lending · credit
- Jun 2024 → Sep 2024RappoVC Analyst InternSan Francisco, CA · venture
03selected project
Probability of Default
an end-to-end credit-risk model
A logistic-regression model that scores default risk for credit-card holders and informs mitigation strategy, built from raw data to a validated, monitored score.
- 01
Vintage & roll-rate analysis to set the performance window and watch delinquency move over time.
- 02
Feature selection Weight-of-Evidence and Information Value, stepwise regression, and clustering, down to a handful of strong predictors.
- 03
Validation for discriminatory power, stability, and accuracy.
- 04
Monitoring with warning and breach thresholds that keep the model honest after launch.
- Python
- Logistic Regression
- WoE / IV
- Vintage Analysis
- Model Validation
- Credit Risk
drag the threshold
- repaid
- defaulted
84%
defaults caught
9%
repaid flagged
30%
all loans flagged
04education & skills
UC San Diego
B.S. Data Science · B.A. Economics
3.75
gpa · out of 4.0
’27
graduating june 2027
tools
- Python
- SQL
- Java
- Tableau
- Snowflake
- Excel
- PowerPoint
finance & risk
- Credit Risk
- Portfolio Risk
- Monte Carlo Simulation
- Financial Modeling
- PD Modeling
- Sensitivity Analysis
certificates
- Securities Industry Essentials
- Bloomberg Finance Fundamentals
- Goldman Sachs Excel Skills for Business
- Financial Reports Analysis
languages
- English (native)
- Chinese (native)
- French (intermediate)
05contact
Say hi.
Recruiter, classmate, or just curious? I’m always happy to talk risk, models, or tide pools.